If you must shop, here are 12 timeless tips. For examples, we’ll use gadgets rather than items like clothing.
1. Know What You Want
If you’re prone to saying “I’ll know it when I see it”, you risk spending lots of time shopping. You also risk overspending. Think about what you want first. You can still browse, but now you have a Plan A. If you like wandering around, you could go for a walk.2. Watch Price Trends
If you don’t have a sense for the normal prices, you can’t tell if you’re really getting a deal. Sales may be based on prices that few would pay.Items may be cheaper when major sales aren’t taking place. Over the years, I’ve noticed (and this is unscientific) that highend computers tend to be cheaper in late November and early December than just after Christmas. There are sales every week, but the deals vary.

You might notice patterns too. If you’re patient, you can win.
3. EXAMINE The Offers
The screenshot shows a Black Friday deal from Dell. On the surface, the deal looks good: a $90 hard drive for $50. I was tempted but looked closer. Does Dell even make hard drives? My Dell computer has disk drives from WD and Samsung. Since no one else sells Dell hard drives, they can set any price they want. The $90 is a “market price”, which is a fictitious. Even so, the offer looks good. However, the product page doesn’t show the warranty.Instead, you’re told “For copy of Ltd Hardware Warranty, write to Dell USA LP, Attn: Warranties, One Dell Way, Round Rock, TX 78682 or see www.dell.com/warranty.”

 If you click through, you’re told something 100% useless: “Dell-branded hardware products purchased in the U.S. or Canada may come with a 90-day, 1-year, 2-year, 3-year, 4-year or 5-year, or other limited hardware warranty.”
In contrast, Costco sells a WD My Passport Ultra hard drive with a three year warranty and carrying case for $90 (1 TB) or $129 (2 TB). Maybe that’s a better deal for peace of mind?
 4. BEWARE OF Substitutes
The Simpsons were once looking for a new TV and kept driving further away to get the best deals. They saw brands like Sorny, Panaphonics and Magnetbox. Some buyers might get fooled by these seemingly familiar brands. Comparing features and specifications isn’t enough either. What matches or wins on paper may not be a good choice. For instance, the tablet may have short battery life or an unresponsive touch screen.
 5. Accept Substitutes
I’m looking for a webcam. My preference is Logitech but there are great choices from companies like Microsoft too. (In this case, I got the top-rated Logitech c920 at Staples today. Lower prices seem unlikely and I’ve lightened Santa’s load.)Flexibility makes shopping easier. There will likely be something on sale when you’re ready to buy.
 6. Watch Sales Cycles
Some items go on sale at specific times of year. For instance, anti-virus software is always on sale on Boxing Day. I don’t know why. A three-user Kaspersky Internet Security suite drops from $80 to $20 at Best Buy. Since the licence lasts a year, this is an annual must-buy item. 
7. Wait After Buying
You might buy on impulse. That’s fine. We’re human. You don’t have to open the product immediately.Wait a day or more. Do you still feel compelled to keep it? If not, return your purchase. This happens to us at Costco where the products keep changing and the return policies are fair.
 8. Know The Return Policy
Shop where you can return purchases easily, without paying for shipping/restocking. I’m reluctant to buy online unless the retailer has physical stores for returns. Sorry Amazon. Especially sorry to smaller retailers (even with physical stores). 
Suppose you bought the hard drive from Dell and decided you didn’t like it. You can return it without cost or penalty.
9. GET Quality
If you’re comfortable buying fewer items, you’ll have less clutter. The environment will thank you too. Quality costs more but what you get is often more enjoyable. I’m still using my iPad 1, which is still working fine.10. Latest or Greatest?
Is last year’s model that bad? Everything becomes old. You might save more by getting last year’s proven model. With gadgets, it’s tempting to get the latest because newer is often better. That’s not true for products like toaster ovens where the changes may be cosmetic.Another option is to get a refurbished model with a full manufacturer’s warranty.
 11. Reduce Choice
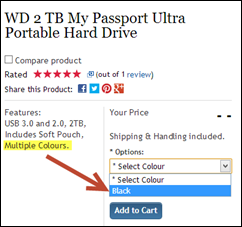
Shopping consumes mental energy. Less choice can be better. For instance, Costco has a limited selection, which is fine. As an example, you can get hard drives in multiple colours but Costco only stocks black. Does that really matter?
12. Ignore THe Hype
We live in the world of buyer beware. We also live in a world where we don’t have to buy. Our basic needs are limited.As George Carlin said, “If you didn’t have so much stuff, you wouldn’t need a house. You could just walk around all the time … your house is a place to keep your stuff while you go out and get … more stuff! Sometimes you gotta move, gotta get a bigger house. Why? No room for your stuff anymore.”
Links
- What lasting gift can you offer everyone you meet?
- Buying a video camera: can we trust the experts?
- How to leverage your philanthropic gifts
- Gift ideas for your business (2007)
- Two ways to show gratitude
Podcast 248
direct download | Internet Archive page | iTunes
PS Just because you have money to spend doesn’t mean you have to spend the money.


